Becoming a homeowner in 2026 : everything you need to know about financial assistance
25 Apr 2026
A rising cost of living, sharply increasing rents, high property prices… becoming a homeowner may seem harder than ever. Yet there are many federal, provincial and municipal programs that can give you a real boost.
Reading time: 7 min
01 / WELCOME TAX
Welcome Tax Refund – Québec
Announced on April 17, first-time buyers in Québec will now benefit from a refundable tax credit covering land transfer duties, the so-called “welcome tax,” up to a maximum of $5,875. The measure is retroactive to January 1, 2026 and applies to properties valued at less than $1M.
In practice, first-time buyers recover the full first $5,000 of transfer duties paid, plus 25% of the excess duties, up to an additional maximum of $875.
For couples, both spouses must not have owned a property in the last four years. The first payments are expected as early as fall 2026.
New: request your tax credit in advance!
Since October 2026, eligible buyers can request an advance payment of their tax credit directly from Revenu Québec, without waiting to file their 2026 income tax return.
To qualify, the request must be submitted in My Account for individuals (Mon dossier pour les citoyens) no later than December 1, 2026.
Note: after this date, you can still claim the credit on your income tax return, but it will no longer be possible to request the advance payment for 2026.
To find out the eligibility conditions and the steps involved, visit the Revenu Québec website.
02 / PREPARING YOUR PROJECT
Budget and Down Payment: The Basics
Before thinking about assistance programs, you need to understand the basic budget. In Canada, the minimum down payment for an owner-occupied property is:
5 % for properties up to $500,000
10% on the portion between $500,000 and $1.5 million
20% for properties of $1.5 million and above
When the down payment is less than 20%, the buyer must purchase mortgage loan insurance (generally through CMHC or Sagen), with a premium ranging from 2.8% to 4% of the amount borrowed.
An important change since August 2024: buyers of a new first home can now benefit from a 30-year amortization (instead of 25 years), which lowers monthly payments and makes homeownership more accessible to millennials and Gen Z.
💡 Good to know:Your borrowing capacity is calculated using the “stress test.” The qualifying rate is the higher of the following two rates:
|
03 / FEDERAL RRSP PROGRAM
The HBP – Home Buyers’ Plan
The HBP is one of the most popular programs. It lets you withdraw money from your RRSP without paying tax, provided you repay it over 15 years.
$ What you can withdraw $
The withdrawal limit is $60,000 per person. For a couple, that means up to $120,000 available for your down payment, with no tax at the time of withdrawal.
1) Who is eligible?
You must be considered a “first-time home buyer,” meaning that neither you nor your spouse has owned a principal residence in the last 4 years, and you must intend to occupy the home as your principal place of residence within one year after buying or building it. The funds must have been in your RRSP for at least 90 days before the withdrawal.
2) I’ve separated. Can I requalify?
Yes! If you sold your property following a separation and have not purchased another property, you may be able to requalify as a “first-time buyer.” Talk to your mortgage advisor.
3) How and when do I repay?
You repay over a 15-year period, at a rate of at least 1/15 of the amount withdrawn per year. Repayment generally begins in the 2nd year following the withdrawal. If you do not repay the annual minimum, the missing amount is added to your taxable income for that year.
04 / FEDERAL FHSA PROGRAM
The FHSA – A Key Program Since 2023
The First Home Savings Account (FHSA) is the most advantageous tool ever created for first-time buyers. Launched in April 2023, it combines the best of the RRSP and the TFSA.
🏆The triple tax advantage
|
Les chiffres clés du CELIAPP

Who can open an FHSA?
You must be a Canadian resident, be between 18 and 71 years old, and not have lived in a property that you or your spouse owned during the previous 4 calendar years.
Can I combine the HBP with the FHSA?
Absolutely! It’s even the ideal strategy to maximize your available funds. By combining an FHSA withdrawal (up to $40,000, non-repayable) and an HBP withdrawal (up to $60,000 per person), an individual can mobilize up to $100,000 for their down payment, and a couple up to $200,000.
💡Strategic tip: Even if you don’t plan to buy right away, open an FHSA now. Contribution room starts accumulating as soon as the account is opened. If you wait a year to open it, you lose $8,000 in unusable contribution room. It’s free and takes 10 minutes. |
05 / TAX CREDITS
First-Time Home Buyers’ Tax Credit
Good news: you are entitled to two tax credits when purchasing your first property, one federal and one provincial. These credits are non-refundable (they reduce the tax you owe, but you won’t receive a cheque if you owe no tax).
🇨🇦 Federal: up to $1,500
🔵 Québec: up to $1,400
Total possible: ~$2,900
📝How to claim itTalk to your accountant to make sure you claim the credits correctly based on your situation. Federal: Enter $10,000 on line 31270 of your tax return for the year of purchase. The credit is calculated at a rate of 15% (= $1,500). If you buy with someone else, you can share the amount. Québec: Complete form TP-752.HA attached to your provincial return. The credit is 14% × $10,000 = $1,400. Usual conditions: not having owned a property in the last 4 years, principal residence in Canada, and you must have tax payable to benefit. |
06 / TAXES ON NEW HOMES
GST/QST Rebate for New Homes
Since March 17, 2026, the federal government fully refunds the GST/QST on new homes valued up to $1M, and reduces the tax payable on properties between $1M and $1.5M. That represents up to $50,000 in savings, no small amount!
Who can benefit?You must be a first-time buyer (not an owner in the last 4 years), buying new, the property must serve as your principal residence, and the contract must have been signed after March 20, 2025. In Québec, the application is made through Revenu Québec, even though this is a federal measure. |
07 / CMHC & ENERGY EFFICIENCY
SCHL — Remboursement de prime pour habitations vertes
Si vous achetez une habitation neuve certifiée écoénergétique ou si vous en faites construire une, la SCHL vous rembourse une partie de la prime d'assurance hypothécaire. C'est un bonus intéressant si vous avez une mise de fonds inférieure à 20 %.
Les taux de remboursement
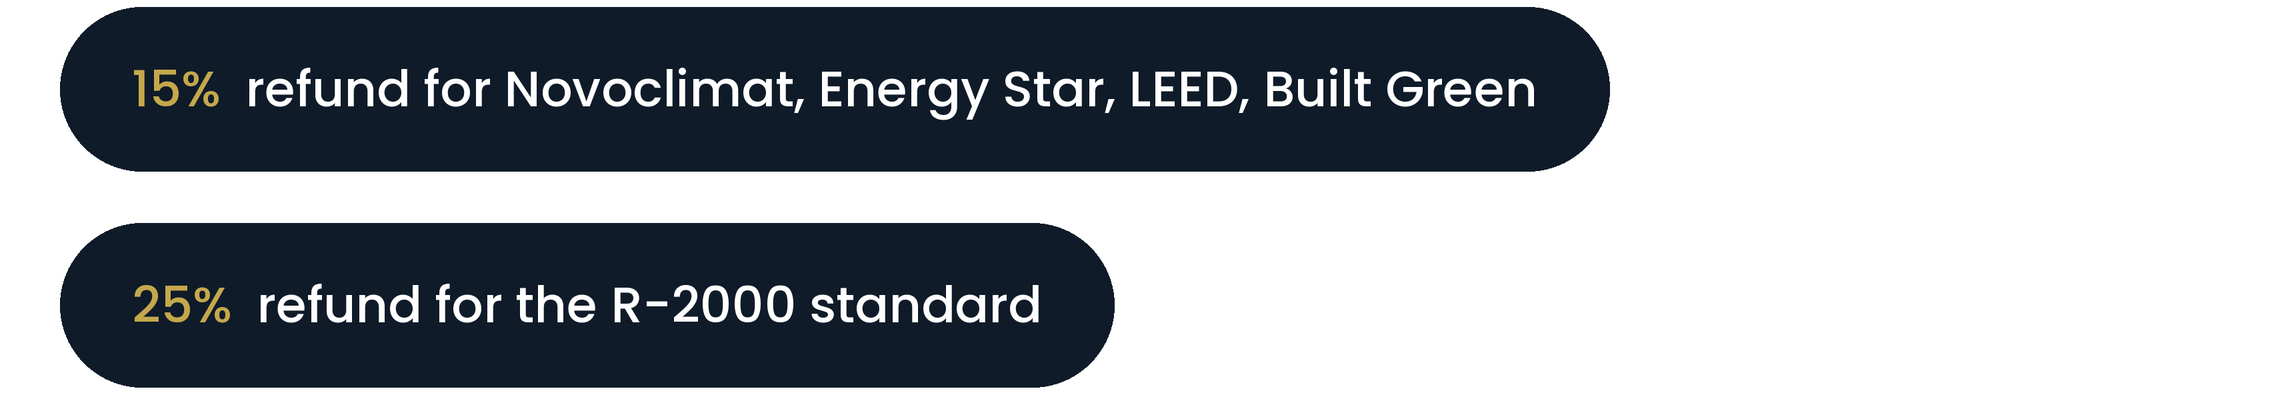
Refund rates : if your CMHC premium is $10,000 and you buy a Novoclimat-certified condo, you recover $1,500. That’s already less out of pocket.
This program is called Eco Plus at CMHC. There is also a variant for existing properties undergoing energy-efficiency renovations of at least $20,000 (taxes included), known as Eco Improvements.
Minimum Down Payment : What You Need to Know For an owner-occupied property of 1 or 2 units, the minimum down payment works as follows:
Example: for a purchase at $760,000, the minimum down payment would be $25,000 (5% × $500,000) + $26,000 (10% × $260,000) = $51,000. For an owner-occupied 3 or 4 unit property, the minimum down payment is 10% (purchase price under $1.5M). For a small rental property of 2 to 4 units (not owner-occupied), expect a 20% down payment, for a maximum purchase price of $1M. |
30-year amortization is available in several situations:
- First-time buyers purchasing a new property
- Second-time buyers (who sold and are buying again) also purchasing a new property
- People going through a divorce or separation, after a 90-day period
Novoclimat Program – Québec
The Novoclimat certification is a provincial program certifying that a new home meets higher energy-efficiency standards. It opens the door to the CMHC refund mentioned above, as well as to the enhancements of the Montréal residential acquisition program.
08 / MUNICIPAL PROGRAMS
City of Montreal Programs
Residential Acquisition Support Program (PAAR)
This is the City of Montréal’s flagship program. It offers direct financial assistance to eligible buyers settling on the island. It comes in two components:
🏠 New property – Lump-sum amount:Who is eligible? Primarily first-time buyers (who have not owned property in Québec during the last 5 years) wishing to acquire a new property. All household types can apply for new construction. Energy-efficiency bonus: +$2,500 if the property is Novoclimat-certified, and +$5,000 if it is LEED-certified. |
🔑 Existing property – Transfer duties refund:For existing properties (resale), the assistance takes the form of a partial refund of the welcome tax, between $5,000 and $7,000. Important condition: your household must include at least one child under 18. The purchase price must not exceed $725,000. ⏱️ Deadline: You have 6 months following the registration of the transaction in the Land Register to submit your application. Don’t miss this window! |
09 / FINANCIAL INSTITUTIONS
Don’t Just Look at the Rate: The Benefits Offered by Financial Institutions
Each financial institution has its own programs to attract buyers. These benefits often go under the radar, but can represent thousands of dollars in additional value.
What to ask your institution:
Cash back: Some banks offer a cash refund (often 1% to 2% of the loan amount) in exchange for a slightly higher rate. Useful for financing renovations or moving costs. Others also offer annual rebates.
Prepayment privileges: Check whether you can repay up to 20% of your principal per year without penalty. This can make a huge difference to your total amortization.
Double-up payments: Certains contrats permettent de doubler votre versement hypothécaire ponctuellement, réduisant drastiquement la durée de votre prêt.
Navigating all these programs can be complex. A mortgage broker can help you quickly identify the ones you qualify for and maximize your benefits. Don’t hesitate to contact us. Our team will always give you the most relevant advice for your situation!
| ⚠️ Important notice: The information in this article is provided for guidance only and reflects the situation in 2026. Government programs may change, be modified or be cancelled. Always consult official sources (canada.ca, revenuquebec.ca, montreal.ca) or a financial professional before making a decision. |
Need help?
Would you like to discuss this with us, or do you need help figuring out how to proceed?
Don’t hesitate to call us at 514 388-9333 or write to us. We’ll explain it all.
In collaboration with Hajer Radhouane, mortgage representative at Desjardins.
Updated on October 30, 2026
